Sewer Backup, Sump Pump & Flood Coverage (NFIP) in Kansas
Sewer backup and sump pump overflow usually need an added endorsement on a Kansas homeowners policy, because a standard policy usually excludes them. Flood damage is generally excluded from a standard policy and usually needs a separate flood policy, often through NFIP. For any waiting period or limit, check your NFIP policy wording, because that wording decides your cover.
24/7 — call any time • Serving 27 Wichita ZIP codes • Local Wichita water damage team
Does a standard Kansas policy cover sewer backup?
Usually, no. Sewer backup coverage Kansas homeowners often lack is one of the most common gaps in a standard homeowners policy in Kansas. Water that backs up through a floor drain, toilet, shower drain, or basement sink is often excluded, even when the backup was sudden and the damage is heavy. The cover that fills this gap is usually an added endorsement, often called water backup coverage, that you add to the policy for an extra charge. That gap matters because a backup can look like ordinary water damage at first glance. The water may be clear at first, then turn dark and foul as the backup grows. A carrier will still ask where the water came from. If it came from a sewer or drain system backing up into the home, the standard policy wording, not the amount of damage, decides whether the loss is covered. If you do not hold the endorsement, the answer is often no, no matter how bad the mess is.
Does a water backup endorsement cover sump pump overflow too?
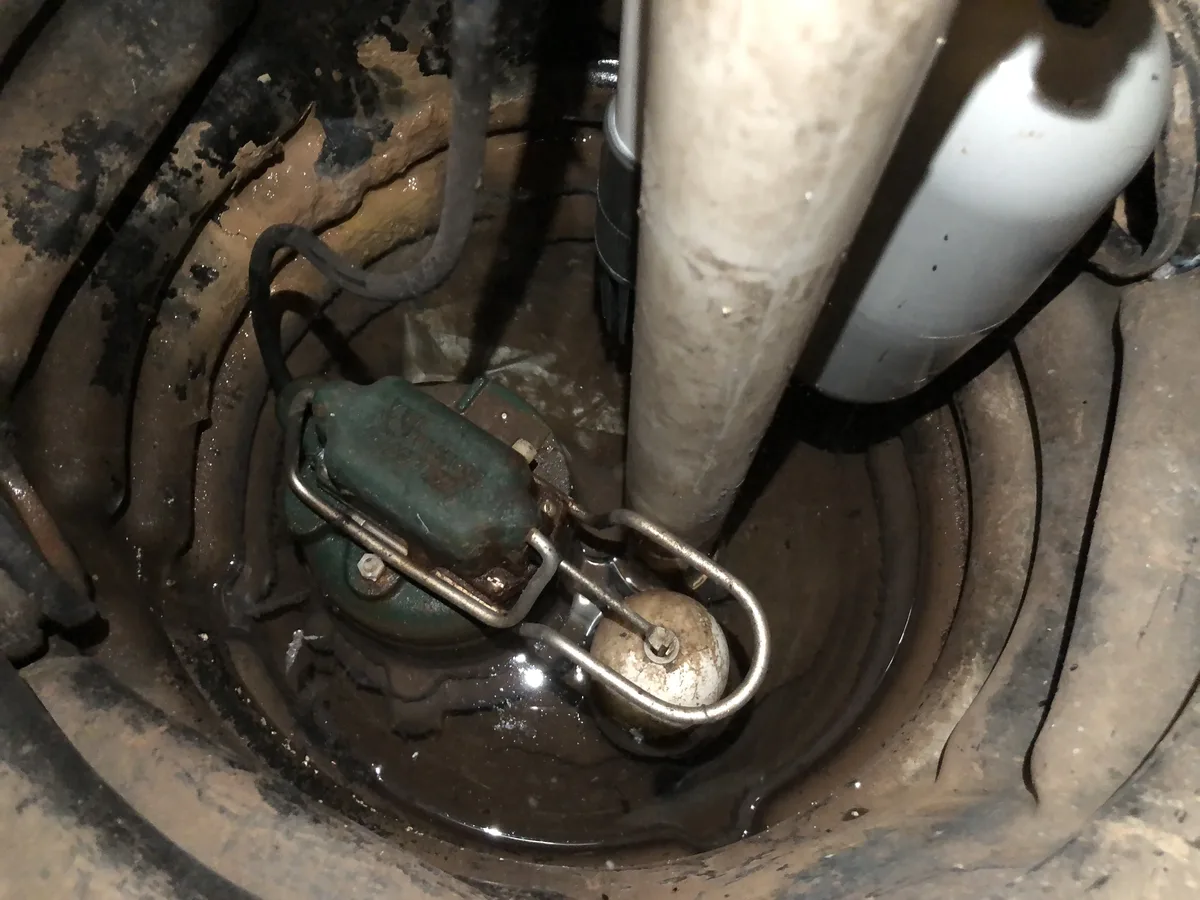
Sometimes, but you must check the wording. Some water backup endorsements cover both sewer backup and sump pump overflow under one limit. Others cover only one of those causes, or they treat a sump pump that lost power differently from a sump pump that failed on its own. The endorsement wording, not the name on the policy summary, decides what you hold. Sump pump overflow is a real Wichita risk. Many Wichita homes have basements, and a sump pit that fills during a heavy storm can overflow fast if the pump stops, loses power, or cannot keep up with the inflow. Clay soil around Wichita homes can hold water against a foundation and add to the load on a sump system after rain. For sewer backup coverage Kansas agents sell as an endorsement, ask your agent three plain questions: does my endorsement cover sump overflow, does it cover a power failure, and what is the dollar limit? Also check whether the endorsement covers cleanup only, or cleanup plus damaged belongings. A finished basement with sheet rock, carpet, furniture, and stored items can run past a low limit fast. If your limit is low, ask what a higher limit would cost before storm season, when you still have time to change it.
Is flood damage covered by a standard homeowners policy in Kansas?
No. Flood damage is generally excluded from a standard homeowners policy in Kansas. That exclusion covers water that comes from outside the home as a flood, such as river flooding, flash flooding, heavy rain that pools and flows across the ground, and water that rises through a basement floor during a flood event. It does not matter whether the water entered through a door, a window well, or a floor drain if the source is flood water. Wichita’s June 2026 flash flood shows how fast flood water can arrive. KSN TV reported up to 6 inches of rain overnight across the Wichita area, 911 took more than 100 flooded-vehicle calls, and Wichita Fire ran 180 calls in 10 hours, with 60 percent water-related. The National Weather Service Wichita page for the 25-26 June 2026 event is the official record for that storm. A homeowner who held only a standard policy during that kind of event would usually have no flood cover for water that came in from outside. Sedgwick County’s water and stormwater factsheet gives useful local background on flood risk, and the Arkansas River and the MS Mitch Mitchell Floodway, known as the Big Ditch, are part of Wichita’s flood control history. Even a home away from a river can flood when streets and storm drains are overwhelmed, so do not judge flood risk by river distance alone.
What is NFIP flood cover, and who can buy it in Kansas?
NFIP stands for the National Flood Insurance Program, a federal flood insurance program that many Kansas homeowners use when a standard policy excludes flood. NFIP policies cover flood damage to a building and, if you buy it, to contents inside the home, subject to NFIP limits and rules. Private flood carriers also sell flood cover in Kansas, and their limits and wording can differ from NFIP, so compare both routes if you are shopping. You do not need to live in a mapped high-risk zone to buy NFIP cover, and many Wichita homeowners outside mapped zones still buy it because flash flooding can hit streets and low areas far from a river. Your agent or a flood insurance agent can tell you whether your community takes part in NFIP, what cover is open to you, and what the premium would be for your home. Ask for the full policy wording, not just a summary, and read the sections on what counts as a flood, what is excluded, and what limits apply to basements. For any waiting period, check your NFIP policy wording. This page does not state a waiting-period number as fact, because the claim seen for a waiting period came only from a vendor blog, not from an official policy source. Your own NFIP policy wording decides when cover starts, so read it before you rely on it for a coming storm.
How do sewer backup, sump overflow, and flood cover differ in practice?
The source of the water is the dividing line. Sewer backup comes from a drain system backing up into the home. Sump overflow comes from a sump pit that fills and spills, often during rain or a power failure. Flood comes from outside the home as rising or flowing water. A single storm can cause all three at once in a basement, and a carrier may treat each source under a different part of the policy, or under a different policy entirely. That is why photos and notes matter from the first hour. Photograph each drain, the sump pit, the water line on the walls, and any water coming in from outside. Note the time you found the water, the time rain started, and whether power was out. Mold can start within 24 to 48 hours on wet materials, according to CDC and EPA guidance, so drying and documentation need to start early, even while you are still sorting out which policy applies. On cost, national figures are labelled NATIONAL here and are not Wichita prices: Bob Vila reported in May 2023 an average job of about $3,455, and PushLeads reported in 2026 an average of about $3,867. No Wichita prices have been published that could be found, so treat those figures only as a national yardstick. Your endorsement limit, your flood limit, and your deductible decide what you pay out of pocket.
What should Wichita homeowners check before storm season?
Check four items before the next heavy rain: whether you hold a water backup endorsement, what limit it carries, whether you hold a separate flood policy, and whether your sump system has a backup power question you still need to answer. That last point is a question to ask our team, not a claim about any product: if power goes out during a storm, what happens to your sump pump, and what backup option fits your home? Our team can look at your pit, your discharge line, and your basement layout and talk through options in plain terms. Also walk your home once before storm season. Clear window wells, check that soil slopes away from the foundation where you can see it, and make sure the sump discharge line runs clear of the house. Those small checks do not change your policy wording, but they can cut the chance of a backup or overflow turning into a full basement flood. Keep your policy papers, your agent’s number, and photos of your basement in one folder you can find in the dark during a storm. For help in the Wichita metro, including ZIP codes 67202 through 67220, plus 67223, 67226 through 67228, 67230, 67232, 67235, and 67260, call ICT Water Pros at (316) 205-2900. Our team can assess a backup or overflow, document the source of the water, and give you a written scope you can share with your carrier.
| Water source | Standard homeowners policy | Cover that usually applies |
|---|---|---|
| Sewer backup through a drain | Usually excluded | Water backup endorsement, subject to its limit |
| Sump pump overflow | Usually excluded | Water backup endorsement, if wording covers sump overflow |
| Flood water from outside | Generally excluded | Separate flood policy, NFIP or private flood |
| Burst pipe inside the home | Usually covered if sudden | Standard policy, subject to deductible and limits |
| Gradual seepage through a wall | Usually excluded | Often no cover; check exclusions in your policy |
Frequently Asked Questions
Is sewer backup already included in my Kansas homeowners policy?
No. A standard policy usually excludes sewer backup, so you need to ask your agent whether you hold a water backup endorsement and what limit it carries.
Does a water backup endorsement cover both sewer backup and sump pump overflow?
Yes, in many cases, but check the wording. Some endorsements cover both sewer backup and sump overflow, while others cover only one, and limits can be low for a finished basement.
Does my homeowners policy cover a flooded basement from street flooding?
Usually, no. Flood water from outside the home is generally excluded from a standard policy, so a separate flood policy is the route most homeowners use for flood cover.
How soon does NFIP flood cover start after I buy a policy?
For any waiting period, check your NFIP policy wording. Do not assume cover starts on the day you buy, and buy before storm season if you can.
What should I do first after a sewer backup in Wichita?
Call our team and your carrier early, take photos, and keep the water out of living areas if you can do so safely. Sewage water needs care, so do not wade through it or run fans that spread it through the house.
Will my endorsement limit pay for a full basement cleanup?
It depends on your endorsement limit and your deductible. Ask for a written scope of work first, then compare it with your limit before work starts, so you know what you may pay out of pocket.
Sources
- Kansas Insurance Department — storm and flood consumer page — Kansas consumer guidance on storm and flood coverage.
- NWS Wichita — 25-26 June 2026 event page — Official event record for the June 2026 Wichita flash flood.
- KSN TV — heavy rain leads to flash flood emergency in Wichita — Reported up to 6 inches of rain overnight across the Wichita area.
- Audacy KNSS — flash flood emergency in Wichita — Local reporting on the June 2026 flash flood emergency.
- CDC — Homeowners and Renters Guide to mold — Mold can start within 24-48 hours on wet materials.
- EPA — Brief guide to mold, moisture and your home — General mold and moisture guidance.
- Sedgwick County — water and stormwater factsheet — Local flood background for Sedgwick County.
- Bob Vila — water damage restoration cost (NATIONAL benchmark) — NATIONAL benchmark only, May 2023, about $3,455 average job; not a Wichita price.
- PushLeads — water damage restoration cost (NATIONAL benchmark) — NATIONAL benchmark only, 2026, about $3,867; not a Wichita price.
Last reviewed: 2026-10-26
Service area: ICT Water Pros serves the Wichita metro across 27 ZIP codes: 67202–67220, 67223, 67226, 67227, 67228, 67230, 67232, 67235, 67260. Location line: Downtown Wichita Area · Wichita, KS 67202. No street address is claimed.
Related Pages
- Home
- How it works
- Water damage cost in Wichita
- Water damage insurance guide for Kansas
- Does insurance cover water damage in Kansas
- Contact ICT Water Pros
- Sump Pump Failure & Basement Flooding
ICT Water Pros — Wichita, KS — Call (316) 205-2900 — Open 24/7